Managing money can feel overwhelming when you have bills to pay, savings goals to meet, and everyday expenses to cover. A simple budgeting method can make it easier to understand where your money goes and decide how to use it wisely.
One popular approach is the 50/30/20 budget rule. It divides your after-tax income into three categories: needs, wants, and savings or debt repayment.
The idea is straightforward, making it a useful starting point for people who want to organize their finances without tracking every dollar. However, the best budget is one that reflects your actual income, living costs, and financial goals.
Here’s how the 50/30/20 rule works and how you can adapt it to your situation.
What Is the 50/30/20 Budget Rule?
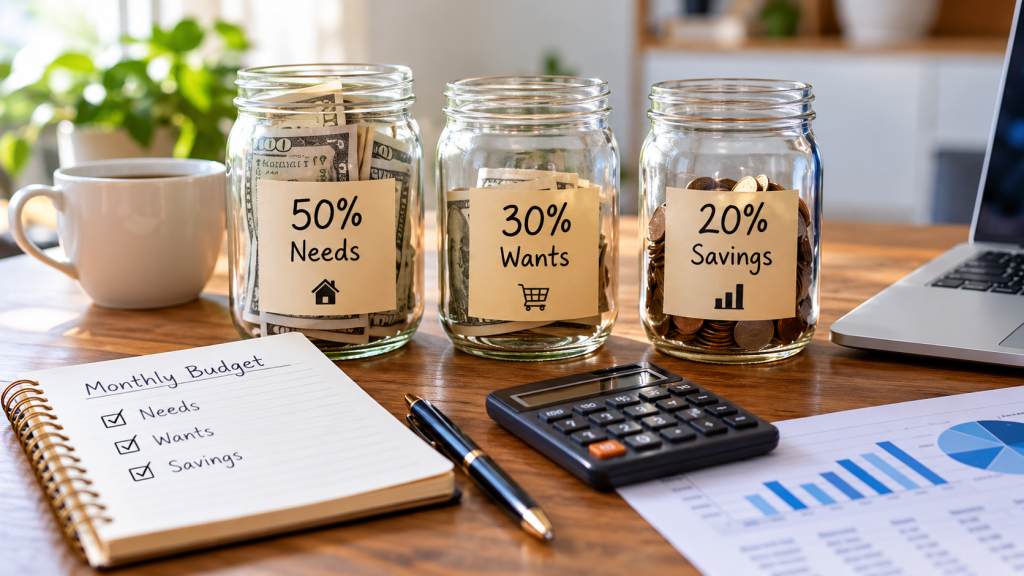
The 50/30/20 rule suggests dividing your monthly take-home income into three categories:
- 50% for needs: Essential expenses you must cover.
- 30% for wants: Optional purchases and activities that make life enjoyable.
- 20% for savings and debt repayment: Money set aside for future goals or used to pay down debt.
For example, if your monthly take-home pay is $4,000, the suggested allocation would look like this:
| Budget Category | Percentage | Monthly Amount |
|---|---|---|
| Needs | 50% | $2,000 |
| Wants | 30% | $1,200 |
| Savings and Debt Repayment | 20% | $800 |
| Total | 100% | $4,000 |
These percentages are guidelines rather than strict requirements. If your housing costs are high or your income varies, you may need to adjust the proportions.
1. Use 50% of Your Income for Needs
Needs are expenses required to maintain your household, meet basic responsibilities, and manage essential financial obligations.
Common examples include:
- Rent or mortgage payments
- Groceries and basic household supplies
- Electricity, water, and other essential utilities
- Transportation to work or school
- Health insurance and necessary medical expenses
- Minimum required debt payments
- Essential childcare expenses
Start by calculating how much you spend on these items each month. Compare the total with 50% of your take-home income.
If your essential expenses exceed that amount, look for realistic ways to reduce costs. You might compare insurance providers, review utility usage, plan meals before shopping, or consider less expensive transportation options.
However, don’t assume every household can keep its needs within 50%. Housing, healthcare, childcare, and other essential costs vary significantly. The goal is to understand your expenses and identify adjustments that are practical for you.
2. Set Aside 30% for Wants
Wants are purchases and activities that improve your lifestyle but aren’t essential for meeting basic needs.
This category may include:
- Restaurant meals and takeout
- Entertainment and streaming subscriptions
- Hobbies and recreational activities
- Nonessential clothing purchases
- Vacations and leisure travel
- Upgrades to electronics or household items
The purpose of this category is not to eliminate enjoyable spending. Instead, it gives you a defined amount to spend without losing sight of your other financial priorities.
Review your recent bank and credit card statements to identify where your discretionary money goes. You may discover that several small recurring expenses account for more than you expected.
Choose the activities and purchases that matter most to you. If dining out is important, for example, you might keep that expense while reducing spending on subscriptions you rarely use.
A realistic budget should leave room for enjoyment while helping you stay within your financial limits.
3. Direct 20% Toward Savings and Debt Repayment
The final 20% is intended to strengthen your financial position over time.
Depending on your circumstances, this portion may go toward:
- Building an emergency fund
- Saving for a home or another major purchase
- Contributing to retirement accounts
- Making additional payments toward high-interest debt
- Saving for education or other long-term goals
If you don’t have emergency savings, building a financial cushion may be a useful first priority. This money can help cover unexpected expenses without immediately relying on borrowing.
If you carry high-interest credit card debt, consider directing some of this portion toward reducing the balance while continuing to make required payments on your other debts.
Once your immediate priorities are under control, you can focus more on longer-term goals, including retirement savings and investing where appropriate.
You don’t need to divide the entire 20% equally among every goal. Choose an allocation that reflects your current needs and adjust it as your circumstances change.
4. Adjust the Rule to Fit Your Income
The 50/30/20 rule works best when it reflects your financial reality.
If you live in an expensive area, essential housing and transportation costs may take up more than half your income. If you have a lower income or significant family responsibilities, saving 20% may not be possible immediately.
In these situations, begin with the amounts you can realistically manage.
For example, you might temporarily allocate 60% to needs, 25% to wants, and 15% to savings and debt repayment. As your income increases or expenses decrease, you can review the proportions again.
If your income changes from month to month, consider building your budget around a conservative estimate of your usual take-home pay. During higher-income months, you may be able to direct additional money toward savings or outstanding debt.
The important thing is to establish a plan you can maintain rather than follow a percentage split that creates unnecessary financial pressure.
5. Track Your Spending and Review Your Budget
Creating a budget is only the first step. Reviewing it regularly helps you understand whether your plan is working.
You can track expenses using a spreadsheet, budgeting app, or simple notebook. Categorize purchases as needs, wants, or savings and debt repayment.
At the end of each month, compare your actual spending with your targets. If one category consistently exceeds its allocation, investigate why before making changes.
For instance, a rise in grocery prices might explain why your needs category has increased. Alternatively, several small subscriptions may be pushing discretionary spending above your target.
Review your budget whenever you experience a major change, such as a new job, a move, a change in household size, or a significant change in expenses.
Even a short monthly review can help you make more informed decisions about your money.
Final Thoughts
The 50/30/20 budget rule offers a simple framework for managing income, balancing everyday spending, and working toward financial goals.
By allocating money to needs, wants, and savings or debt repayment, you can develop a clearer picture of your finances without making budgeting unnecessarily complicated.
Remember that the suggested percentages are starting points, not rigid rules. Your ideal budget may look different depending on your income, location, responsibilities, and priorities.
Start by calculating your take-home pay, reviewing your expenses, and choosing one practical improvement to make this month.
A good budget isn’t about following perfect percentages. It’s about giving your money a purpose and building habits that support your financial future.