Unexpected expenses can happen at any time. A car repair, medical bill, broken household appliance, or temporary loss of income can quickly put pressure on your finances. When money is already tight, even a relatively small expense can become difficult to manage.
That’s why having an emergency fund can be so valuable. It provides a financial cushion that can help you handle unexpected costs without immediately relying on credit cards, personal loans, or money intended for other bills.
But how can you save money when most of your paycheck is already committed to everyday expenses?
The good news is that you don’t need a large salary or hundreds of dollars in extra cash to get started. With a realistic plan and a few consistent habits, you can begin building emergency savings at your own pace.
Here are seven practical steps to help you get started.
1. Start With a Small, Achievable Goal
One of the biggest mistakes people make when starting an emergency fund is setting a goal that feels impossible to reach.
You might hear recommendations to save three to six months of essential living expenses. While that can be a useful long-term target, it may feel overwhelming if you’re living paycheck to paycheck.
Instead, start with a smaller milestone.
Your first goal might be $100, $250, or $500, depending on what you can realistically afford. Even a modest amount can help cover certain unexpected expenses, such as a minor car repair or an urgent household purchase.
Once you reach your first target, choose the next one.
Breaking a large goal into smaller steps can make saving feel more manageable and help you stay motivated as your balance grows.
Remember, the purpose of your first emergency fund is to give you a little more financial breathing room, not to solve every possible problem immediately.
2. Review Your Monthly Expenses
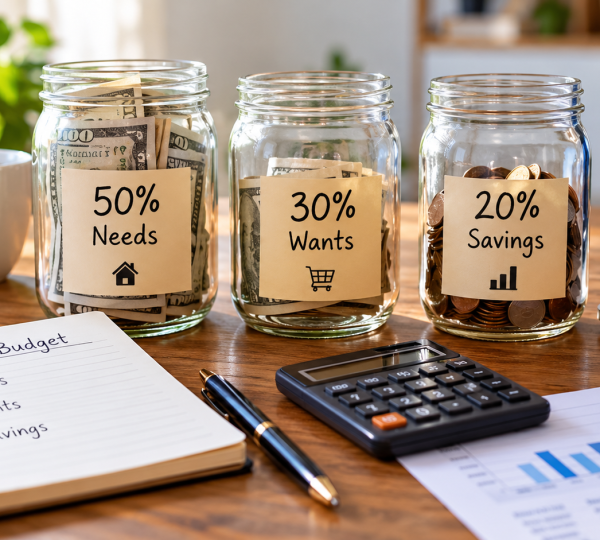
Before deciding how much to save, take a closer look at where your money goes each month.
Write down your take-home income and your regular expenses, including rent or mortgage payments, groceries, utilities, transportation, insurance, and debt payments.
Then review your discretionary spending.
You may find opportunities to reduce expenses such as unused subscriptions, frequent takeout orders, impulse purchases, or memberships you rarely use.
For example, canceling a $15 monthly subscription and reducing takeout spending by $20 could free up $35 each month.
That may not seem like much, but it adds up to $420 over a year if you maintain those savings.
You don’t need to eliminate every enjoyable activity. Focus on changes that are realistic and sustainable rather than creating a budget that leaves you feeling deprived.
If your essential expenses already consume nearly all your income, don’t blame yourself. There may be limited room to cut costs, and you may need to focus on increasing income or finding assistance with essential bills.
3. Save a Small Amount From Every Paycheck
Consistency is often more important than the size of your first contribution.
Instead of waiting until the end of the month to see whether you have money left over, consider setting aside a small amount whenever you receive your paycheck.
For example, saving $10 each week adds up to $520 over a year, before any interest. Saving $25 each week adds up to $1,300 over the same period.
Choose an amount that won’t prevent you from paying essential bills or meeting necessary financial obligations.
If your income changes from month to month, you can adjust your contributions accordingly. Save a little more during stronger months and reduce the amount when money is particularly tight.
The goal is to build a habit you can maintain without creating additional financial stress.
4. Keep Your Emergency Savings Separate
Keeping emergency savings separate from your everyday spending money can make it easier to avoid using the funds for nonessential purchases.
For many people, an appropriate savings account at a federally insured bank or credit union in the United States is a practical option.
Look for an account with low or no maintenance fees, convenient access to your money, and a competitive interest rate.
You generally want emergency savings to be accessible when needed rather than tied up in investments that can fluctuate in value.
Consider giving the account a clear name, such as “Emergency Fund.” Seeing its balance grow can help reinforce your goal.
If possible, arrange an automatic transfer from your checking account after payday. Even a small recurring transfer can help make saving part of your routine.
However, check your account balance and upcoming bills before scheduling transfers to avoid overdraft fees or missed payments.
5. Put Unexpected Extra Money to Work
Occasionally, you may receive money that wasn’t part of your regular budget.
This could include a tax refund, a work bonus, a cash gift, a rebate, or money from selling unused household items.
Consider directing some or all of this extra money toward your emergency fund.
For example, if you receive a $300 tax refund, you could use part of it for an immediate financial need and put the remainder into savings.
You don’t have to save every unexpected dollar. The right decision depends on your current obligations and priorities.
If you have overdue essential bills or high-interest debt, you may need to balance those responsibilities with building a small cash reserve.
The important thing is to make a deliberate choice rather than allowing every extra dollar to disappear into unplanned spending.
6. Know What Counts as an Emergency
An emergency fund works best when you establish clear rules for using it.
Appropriate reasons to withdraw money may include an urgent medical expense, an essential car repair needed to get to work, emergency home repairs, or a temporary loss of income.
Planned expenses, such as holidays, birthday gifts, annual insurance premiums, and routine vehicle maintenance, generally belong in separate savings categories.
These costs may be important, but they are often predictable enough to plan for in advance.
Keeping emergency savings reserved for genuine unexpected needs helps preserve the fund for situations when you need it most.
If you do have to use the money, don’t view it as a failure. That’s precisely what the fund is designed to do.
Once the emergency has passed and your finances stabilize, you can begin rebuilding your savings.
7. Gradually Build Toward a Larger Safety Net
After reaching your initial savings goal, continue building your emergency fund as your budget allows.
A common longer-term target is three to six months of essential living expenses. However, the appropriate amount depends on your circumstances.
Someone with a stable job and relatively low fixed expenses may need a different cushion from someone who is self-employed, supports dependents, or has an unpredictable income.
Calculate your essential monthly expenses and use that figure to establish a realistic target.
For example, if your essential expenses total $2,000 per month, three months of expenses would equal $6,000.
You don’t need to reach that amount quickly. Continue contributing regularly, increase your savings when your income grows, and review your target as your responsibilities change.
Progress may be slow at first, but every contribution moves you closer to having a stronger financial safety net.
Final Thoughts
Starting an emergency fund when money is tight can be challenging, but you don’t need to wait until your finances are perfect to begin.
Start with a small goal, review your expenses, save what you reasonably can, and keep your money somewhere accessible. As your circumstances improve, gradually increase your contributions and work toward a larger financial cushion.
There may be months when saving is difficult or impossible. That’s okay. Your budget should reflect your actual situation, and protecting your essential needs comes first.
An emergency fund isn’t built overnight. It’s built through small, realistic decisions that help you prepare for the unexpected, one contribution at a time.