A personal loan can help cover a major expense, consolidate existing debt, or pay for an unexpected bill. However, borrowing money also creates a financial commitment that can affect your monthly budget for months or even years.
Before applying, it’s worth taking time to understand the costs, compare your options, and decide whether a loan fits your financial situation. Looking beyond the advertised interest rate can help you avoid surprises and make a more informed decision.
Here are six important questions to ask yourself before taking out a personal loan.
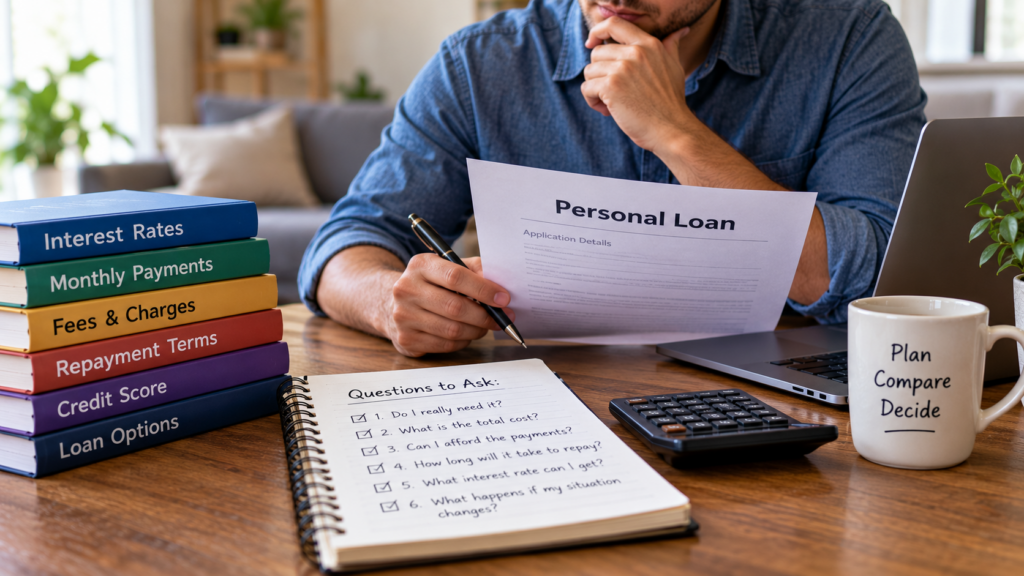
1. Do I Really Need to Borrow This Money?
Start by identifying why you need the loan and whether borrowing is the most suitable option.
For example, you might be considering a personal loan to cover an essential home repair, manage a large medical expense, or combine several high-interest debts into one payment.
Before applying, consider whether you could cover the expense using existing savings, a payment plan, or another lower-cost option. Using savings may make sense for some expenses, but avoid exhausting your emergency fund if doing so would leave you financially vulnerable.
If you’re borrowing to consolidate debt, compare the total cost of the new loan with the cost of your existing balances. A lower monthly payment doesn’t necessarily mean you’ll pay less overall, especially if the repayment period becomes longer.
Understanding the purpose of the loan can help you decide whether borrowing is necessary and how much you actually need.
2. What Is the Total Cost of the Loan?
The advertised interest rate is important, but it doesn’t tell you everything about the cost of borrowing.
In the United States, lenders generally disclose the annual percentage rate (APR), which incorporates the interest rate and certain loan fees. The APR can help you compare offers, although you should also review the complete loan terms.
Check for charges such as origination fees, late payment fees, and any applicable prepayment penalties. Some lenders deduct an origination fee from the loan proceeds, meaning you may receive less money than the amount you borrow.
For example, if you borrow $10,000 and an origination fee is deducted before the funds are paid to you, the amount deposited into your account may be less than $10,000, even though your repayment obligation is based on the loan terms.
Ask the lender for a clear breakdown of the APR, fees, monthly payment, and total amount you will repay over the life of the loan.
3. Can I Comfortably Afford the Monthly Payments?
A loan payment may look manageable on its own, but it needs to fit alongside your existing financial responsibilities.
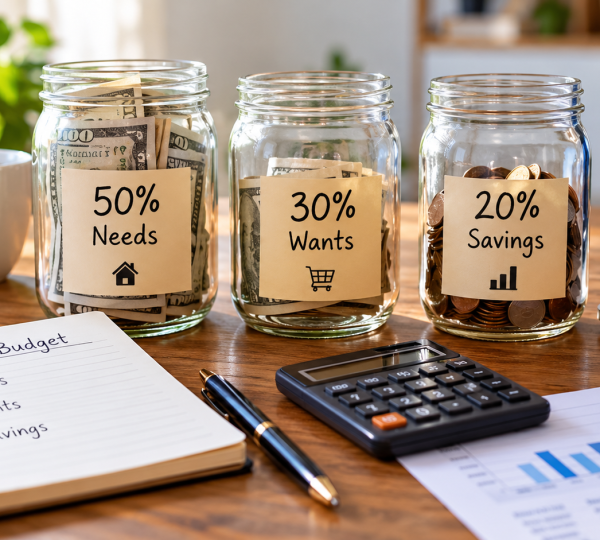
Review your monthly take-home income and subtract essential expenses, including housing, groceries, utilities, transportation, insurance, and existing debt payments. Then consider irregular expenses and the amount you want to save each month.
For example, a $250 monthly loan payment represents $3,000 in payments over 12 months, before considering any other applicable costs. Make sure the payment fits your budget without forcing you to rely on additional borrowing.
It’s also wise to consider what might happen if your income decreases or an unexpected expense arises. A payment that is affordable today may become difficult if your circumstances change.
If the proposed payment leaves little room for essential expenses or emergency savings, consider borrowing less, delaying the expense, or exploring other options.
4. How Long Will It Take to Repay the Loan?
Personal loans may offer different repayment periods, depending on the lender and the amount borrowed.
A longer repayment term often results in a lower monthly payment, but it can also increase the total interest paid over time. A shorter term may cost less in interest but require higher monthly payments.
For example, imagine two loan offers with the same principal and interest rate but different repayment periods. The loan with the longer term would generally have smaller scheduled payments, while the shorter-term loan would generally be repaid sooner and accumulate less interest.
Compare the monthly payment and total repayment amount for each offer rather than choosing solely based on the smallest payment.
Look for a repayment period that balances affordability with the overall cost of borrowing. Also, check whether the loan allows early repayment without a penalty if you expect to pay it off ahead of schedule.
5. What Interest Rate Can I Qualify For?
Personal loan interest rates can vary depending on your credit history, income, existing debts, loan amount, repayment term, and the lender’s criteria.
Before applying, review your credit reports and check them for errors. In the United States, you can access free credit reports through the federally authorized website AnnualCreditReport.com.
Comparing offers from several lenders may help you find more suitable terms. Where available, ask whether you can check potential rates through prequalification using a soft credit inquiry, which generally does not affect your credit scores.
Submitting a formal application may involve a hard credit inquiry. Multiple applications can affect your credit, although certain scoring models treat qualifying loan inquiries made within a specific shopping window as a single inquiry.
Don’t assume you’ll receive the lowest advertised rate. Review the actual offer you qualify for, including its APR, fees, and repayment conditions, before making a decision.
6. What Happens If My Financial Situation Changes?
Before signing a loan agreement, understand your responsibilities if you experience a job loss, unexpected medical expense, or another financial setback.
Ask the lender what happens if you miss a payment, whether hardship assistance is available, and whether payment deferrals or modified repayment arrangements may be offered. These options are not guaranteed, so review the agreement and ask for the lender’s policies in writing.
Late or missed payments can lead to fees, collection activity, and negative credit reporting. Depending on the loan terms, continued nonpayment can have more serious financial and legal consequences.
It’s also important to understand whether the loan is secured or unsecured. Most traditional personal loans are unsecured, meaning they don’t require collateral, but some lending products may be secured by an asset.
Knowing the consequences before borrowing can help you prepare for difficulties rather than trying to understand your options after a problem occurs.
Final Thoughts
Taking out a personal loan is a decision worth making carefully. By asking whether you need to borrow, understanding the total cost, checking affordability, comparing repayment terms, reviewing available interest rates, and preparing for possible financial changes, you can make a more informed choice.
Take time to compare lenders and read the loan agreement before signing. If the payment doesn’t fit comfortably into your budget, consider borrowing less or exploring alternatives.
The right borrowing decision isn’t simply about getting approved. It’s about choosing loan terms you understand and can reasonably manage throughout the repayment period.